What is Exclusive Provider Organization (EPO) Insurance
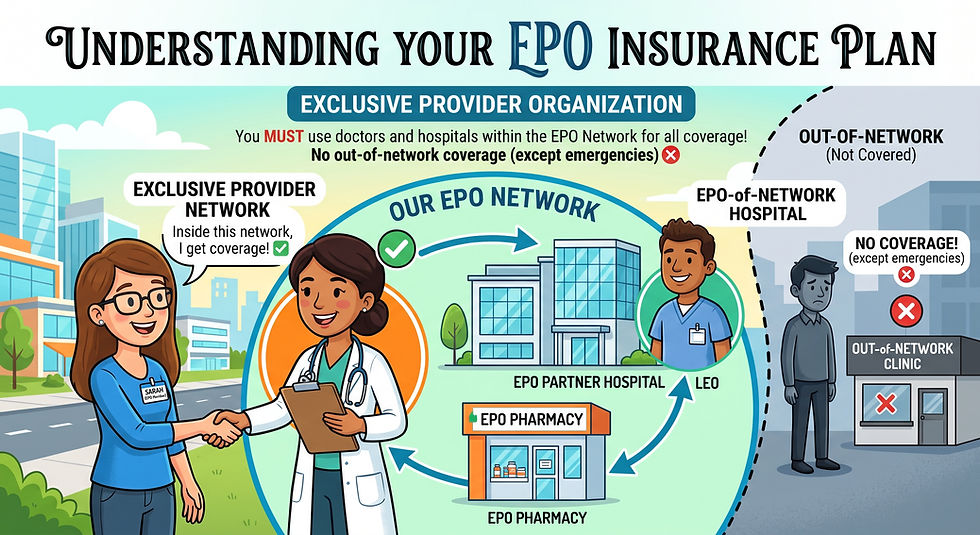
An Exclusive Provider Organization (EPO) is a health insurance plan that mandates using a designated network of doctors, hospitals, and specialists to have your care covered.
It serves as a middle ground between an HMO (Health Maintenance Organization) and a PPO (Preferred Provider Organization)—adopting the strict network rules of an HMO while offering some of the flexibility of a PPO.
Here's an overview of how an EPO functions and its main characteristics:
Key Features of an EPO
1. No Out-of-Network Coverage
With an EPO, out-of-network care isn't covered except in genuine emergencies. If you opt for a doctor or hospital outside the network for regular care, you'll bear the full cost yourself.
2. No Primary Care Physician (PCP) Required
Unlike an HMO, most EPO plans don't require selecting a Primary Care Physician to manage your healthcare.
3. No Referrals Needed for Specialists
Without a PCP gatekeeper, you can directly consult a specialist without needing a referral. You can book an appointment with a dermatologist, cardiologist, or physical therapist, provided they are within the EPO network.
Comparing EPOs to HMOs and PPOs
To understand how an EPO fits into the insurance landscape, a side-by-side comparison is helpful:
Feature | HMO | EPO | PPO |
Out-of-Network Coverage? | No (Emergency only) | No (Emergency only) | Yes (But you pay more) |
Need a Designated PCP? | Yes | No | No |
Referrals Required for Specialists? | Yes | No | No |
Premium Cost | Typically Lowest | Moderate | Typically Highest |
Pros and Cons of an EPO
The Benefits
Lower Premiums than PPOs: The insurer negotiates reduced rates with a smaller, exclusive network, passing those savings to you through lower monthly premiums.
Direct Access to Specialists: You avoid the hassle and time of visiting a primary doctor just to obtain a referral to see a specialist.
Large Managed Networks: Many modern EPOs use extensive national networks, offering plenty of local options to choose from.
The Drawbacks
No Flexibility Outside the Network: If your preferred doctor leaves the network or you wish to see a top specialist who isn't a member, you bear the financial responsibility entirely.
Geographic Limitations: If you frequently travel outside your plan's service area, you'll only be covered for emergency room visits, not routine or urgent care.
Who is an EPO best for?
An EPO is often ideal if you seek lower monthly costs but dislike the hassle of obtaining doctor referrals. It's particularly suitable if you're diligent about ensuring your doctors are in-network or if you reside in a major metropolitan area with a high concentration of in-network healthcare systems.
Please contact me for more information.
(626) 702-1399
CA Insurance License #4505589
Comments